This is a restatement of a report published November 11, 2026, at 09:41 (UTC+8). Alea Research wrote the research; 深潮 TechFlow compiled it. Figures, thresholds, and forward dates are those given then. December 2026 and early 2027 items were still ahead of that publication and are not updated here.
What the chain is
Robinhood Chain is built on the Arbitrum technology stack and has no native token. As with Coinbase on Base, Robinhood collects on-chain gas, but it does not keep the full receipt. Arbitrum charges a 10% technology licensing fee on total network fees. The article treats that fee as a license payment. It does not claim that Robinhood Chain shares Arbitrum One’s security.
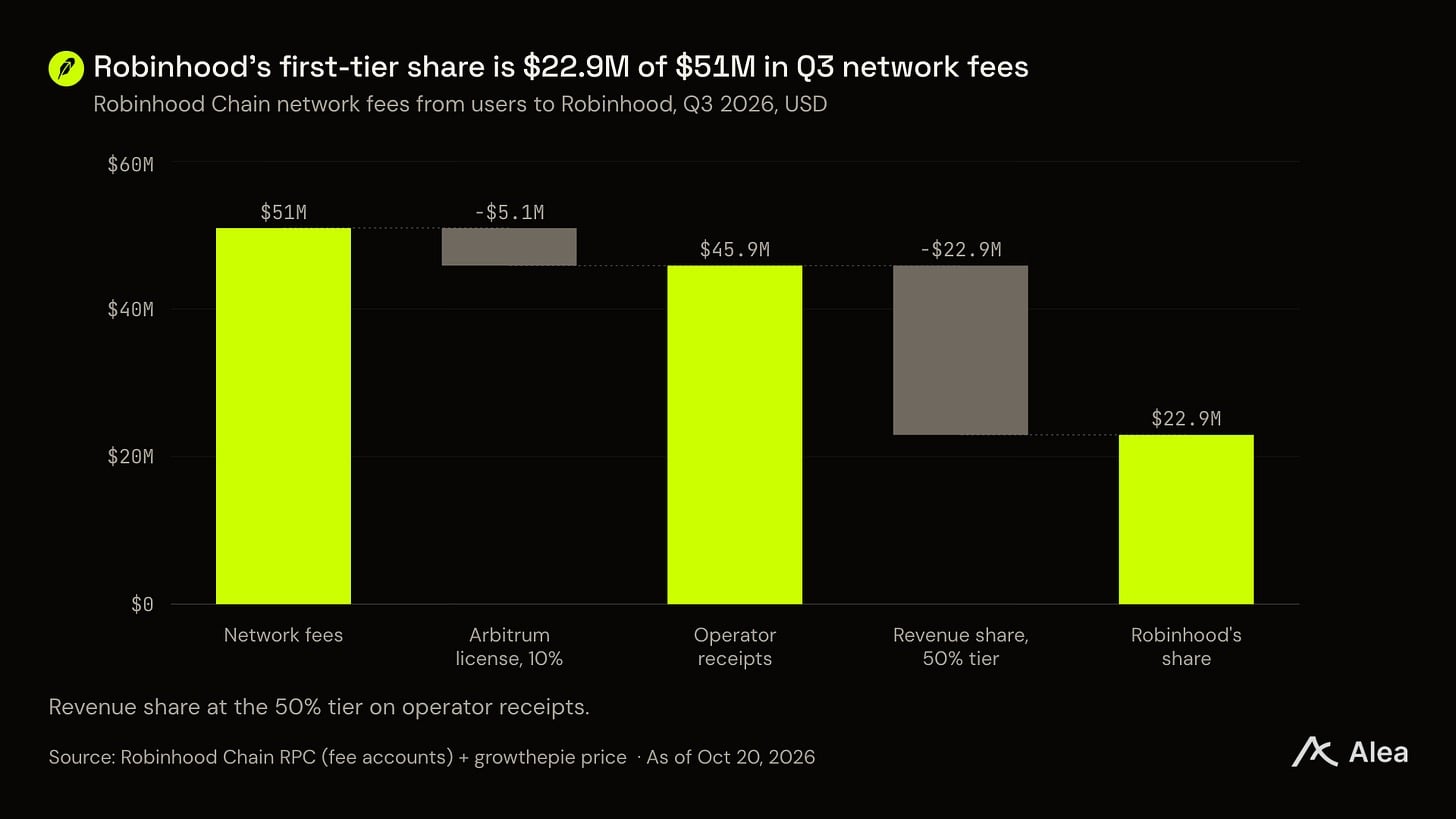
The remainder uses a tiered split. Until cumulative operating revenue reaches about $50 million, Robinhood retains 50%. As revenue scale grows, that retention rate is set to rise to 70% and then 85%. Measured at the first-tier 50% rate, Alea put Robinhood’s Q3 share at $22.9 million. A chart in the article shows the allocation of the quarter’s $51 million in network fees after the 10% Arbitrum license fee and that 50% tier.
The same report says that after October 26, cumulative operator revenue was still $2.9 million short of the about $50 million threshold. It does not redefine that base beyond those two statements.
Q3 2026 fees, with and without the launch wave
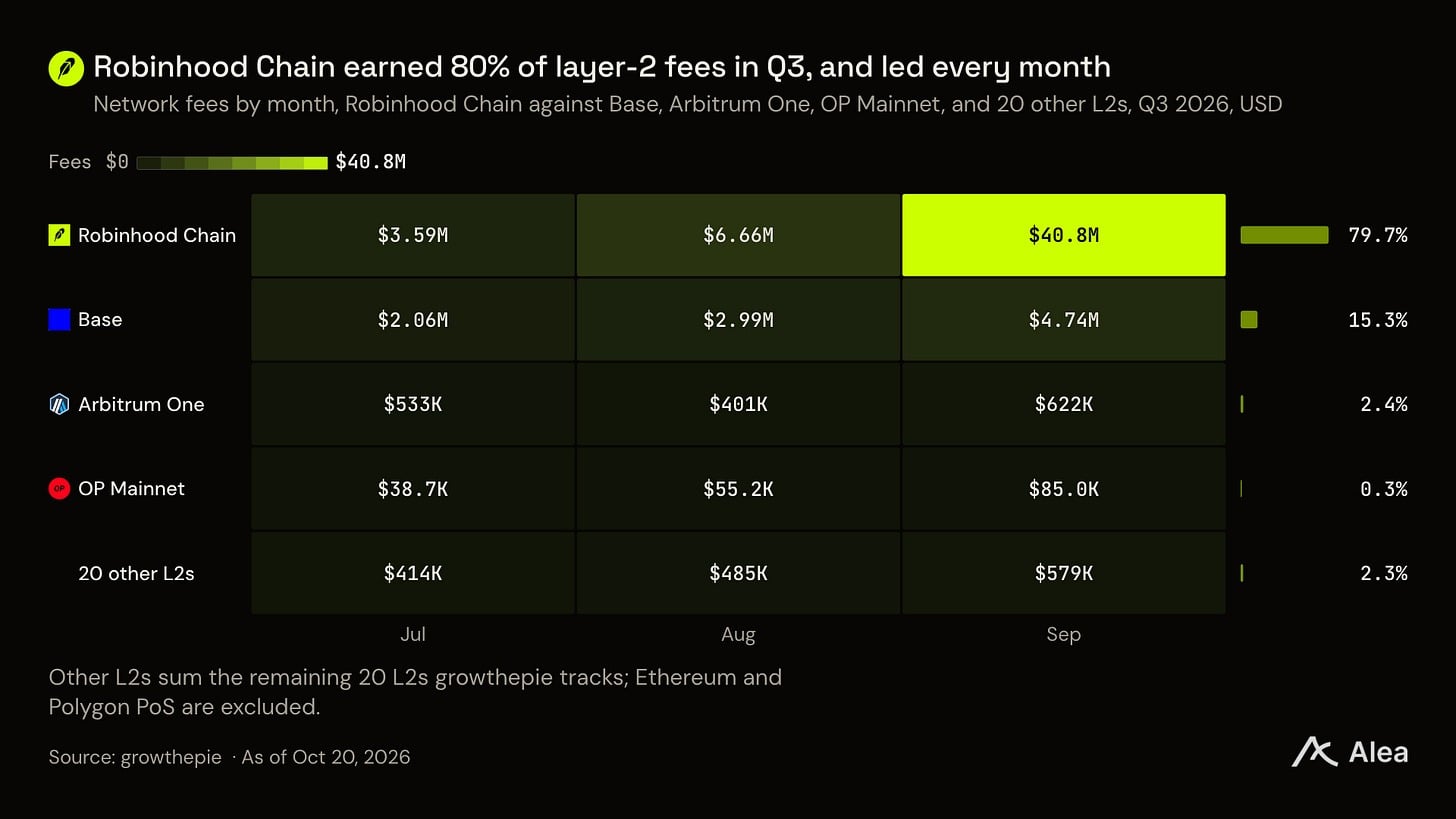
Q3 2026 was the first public quarter after mainnet. Alea reported that Robinhood Chain took 80% of Ethereum Layer 2 network-fee revenue. TechFlow’s introduction described the same result as about 80%. A chart sourced to growthepie compares monthly network fees for Robinhood Chain, Base, Arbitrum One, and OP Mainnet; the article text does not list a dollar total for each month.
On-chain exchange volume on the chain was $90.7 billion, above the $50 billion of crypto volume matched by the Robinhood app and Bitstamp combined.
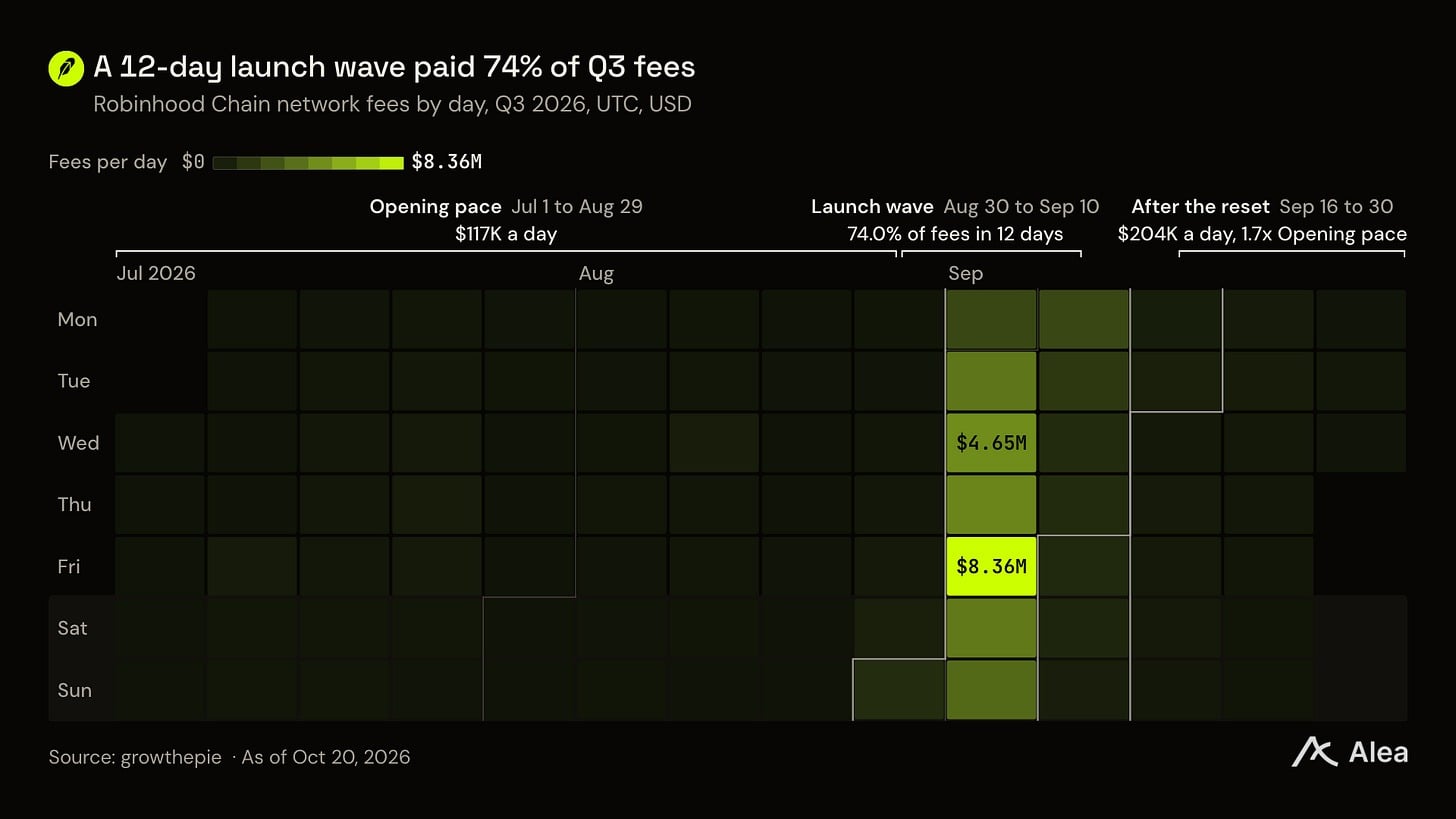
A token-launch wave contributed 74% of this chain’s network fees. Excluding that 12-day wave, Robinhood Chain still accounted for 57.7% of all L2 network fees over the other 80 days of the quarter, compared with 30.7% for Coinbase’s Base. By the last week of September, average daily fees had fallen back to the level of July 1 through August 29.
Further figures from the same write-up:
- With or without the launch wave, Robinhood Chain ranked first among L2s in network fees. Its Q3 total was $51 million. The median L2 network-fee figure was $24,700.
- The $22.9 million first-tier share equaled 19% of Robinhood’s $120 million in total crypto-business revenue for the quarter.
- Traders paid $593 million in application-layer fees, separate from L2 gas. Application operators retained $147 million of that.
- After a governance proposal passed, the Uniswap protocol-fee switch was activated on this chain on July 27. Through September 30 it had funded buybacks and burns of UNI worth $13.7 million.
- In September, returning active addresses exceeded Base. Total value locked in on-chain applications reached a reported high of $1.15 billion on October 22.
Who set the gas ceiling
Average gas per transaction on Robinhood Chain in the quarter was 6.4 cents, against 1.4 cents before the launch wave. Launch platform Pons released a V2 factory contract on August 4 and completed 648,701 token launches in total. Gas use was pushed above the preset target, and the base fee rose with the backlog of transactions.
A daily-fee heatmap in the article marks August 30 through September 10 as the period that produced 74% of quarterly network fees. The busiest day, September 4, brought in $8.36 million, more than twice July’s entire total. Alea called the move specific to Robinhood Chain: versus the prior 12 days, Pons V2 fee revenue rose 7.3 times, while pump.fun fell 33% over the same stretch.
Within three days Robinhood raised the network gas-target ceiling twice, to 40 million gas per second, and on October 18 lowered it to 15 million. Alea’s conclusion is that those capacity settings directly determined most of the chain’s Q3 fee volume. That is an operator control, not a property of the tokens launched on Pons.
In the last week of September, average daily network fees were $121,000: close to the early post-launch pace in dollars, and 24% lower in ETH. From October 1 through October 19 the daily average fell to $54,600, less than half the early level, and gas used by the launch platform dropped by as much as 91%. Gas prices returned to the bottom of the range after the wave; returning active addresses stayed firm.
Route 1: stock tokens, minted only by Bitstamp
From July to September, stock tokens’ share of DEX volume on the chain rose from 2.6% to 15.6%.
The report describes Robinhood’s stock tokens as tokenized US equities that are debt certificates, fully collateralized one-for-one by the underlying shares, and minted only by Bitstamp, a Robinhood company. They are a represented claim, not the share. The article does not describe the share as locked, burned, or messaged onto the chain. Bitstamp mints the token; secondary trading does not itself mint or redeem the collateral.
In September, volume in pairs of tokens that were not new issues reached $8.7 billion, above bStocks at $6.4 billion.
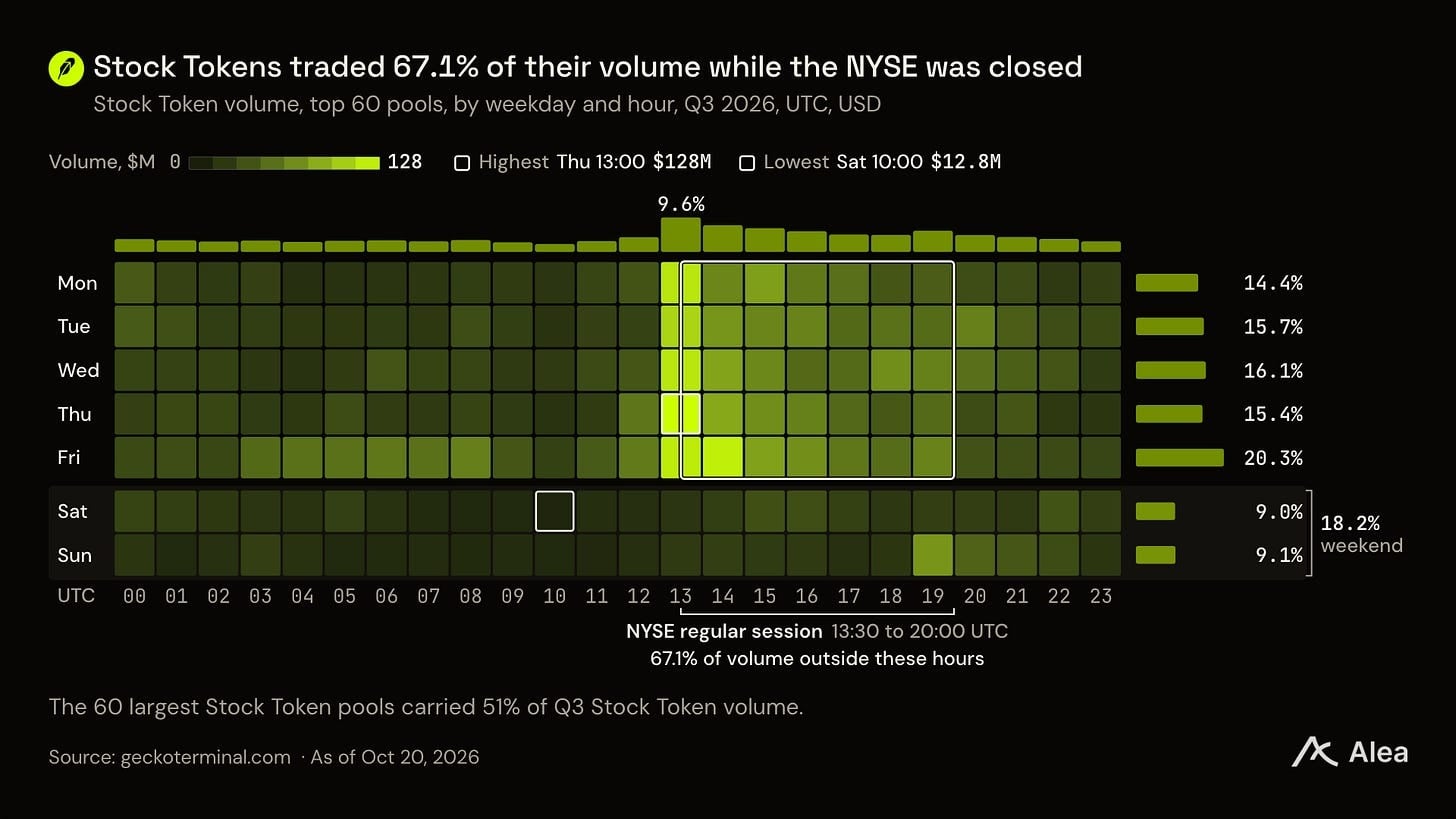
Among the 60 largest stock-token pools by volume, 67.1% of Q3 volume occurred while the New York Stock Exchange was closed. The two weekend days alone accounted for 18.2%, and during that time the channel for minting and redeeming the underlying shares was closed. Off-hours trading still produced a price. In the 30 minutes before the Monday open, all 37 weekend and holiday moves of at least 1% were pointed in the correct direction by the tokens, and the median pricing of the size of the move was 86%. At the September NYSE close, the median difference between the ten most active stock tokens and the underlying share prices was 13 basis points, narrower than 29 basis points in July.
The trust boundary is the issuer and the session clock. Only Bitstamp mints. When the cash-equity mint and redeem window is shut, the DEX can still trade a representation whose supply is not changing through that window.
The report says Robinhood plans to open voting for qualified holders and redemption of tokens for the underlying shares, with no timetable set. A US SEC rule order published on September 17 allows compliant US venues to trade tokenized stocks that carry dividend and voting rights. Those are rights this product did not have.
Two later handoffs, still separate from that mint
On October 22, Morpho and Robinhood jointly opened a lending market that lets holders borrow stablecoins against stock tokens as collateral. The loan depends on the token and on Morpho. It does not replace Bitstamp as sole minter or change the collateral arrangement described above.
On October 27, Ondo brought 15 tokenized stocks and ETFs onto the chain. Eleven of them trade in Uniswap pools paired directly with the corresponding Robinhood stock tokens. Ondo opens cross-chain minting and redemption of those 11 assets every day on Ethereum and on BNB Chain, including weekends. That is a different issuer and a different window: Ondo’s mint and redeem stay open on weekends, while Bitstamp’s mint and redeem for Robinhood stock tokens do not when the underlying share channel is closed. The article does not describe shared security between the two representations. A pool that pairs them is a market link, not one asset.
Separately, at the start of operating day 92, Robinhood Earn’s Steakhouse vault on Morpho had $499 million under management, 18% more than Coinbase’s lending vault at the same number of days after launch.
Dates the November 11 report left ahead
In its October 27 earnings report, Robinhood listed the chain among the top five public chains by revenue and trading volume. Alea then marked three checkpoints:
- December 25, 2026. At the October pace, this date would trigger the 70% retention tier. After October 26, cumulative operator revenue was $2.9 million short of the about $50 million threshold. Crossing it would give Robinhood a higher share of each new dollar of network fees.
- December 31, 2026. The wallet gas subsidy was due to expire. Until then, Robinhood Wallet paid gas in full on swaps larger than $0.50. January 2027 would be the first reading of average daily fee demand without that subsidy.
- Early 2027. Subject to regulatory approval, Robinhood planned to offer weekend US equity trading inside its app to US users who cannot yet hold stock tokens. That is an app feature for people outside the token, not a transfer of the stock token to them.
What Alea counted after gas cooled
Alea’s close: in Q3 2026, no other L2 took in more network fees than Robinhood Chain, whether or not the launch wave is included. The surge supplied the peak. Under it, stock tokens’ share of trading rose month by month, and before the opening bell the tokens pointed to Monday’s direction.
Even with October gas revenue already low, $683 million of USDG sat on the chain. Alea calculated income on the underlying Treasury reserves at Treasury-bill rates at about $26.9 million a year, and described that figure as three times Robinhood’s own gas share. As the retention tier moved up, Robinhood’s increment on each additional fee dollar would rise further. The $26.9 million is that rate-based calculation in the report, not a separate cash total presented as already collected.
Original article: TechFlow, November 11, 2026.